Your insurance company sent a letter about your roof. Now what?
A roof letter from your insurer has a deadline. Answer it with facts about the roof, not panic.
In this guide
The short answer
A letter from your home insurer about the roof usually means one of three things: they want photos, they want a repair, or they plan not to renew the policy. Each one comes with a date. The date is the part that matters most.
Do not ignore it and do not panic-sign the first roof contract that shows up. Find the deadline, ask the company for the exact reason in writing, and get the roof looked at by someone who will photograph what is actually there. Then decide.
The letter starts a clock. Facts about your roof are how you answer it.
Why these letters show up
Insurance companies review homes at renewal. Some send a person. Many now look at aerial or satellite images of the roof and flag what they think they see: discoloration, missing material, patches, tarps, debris or wear.
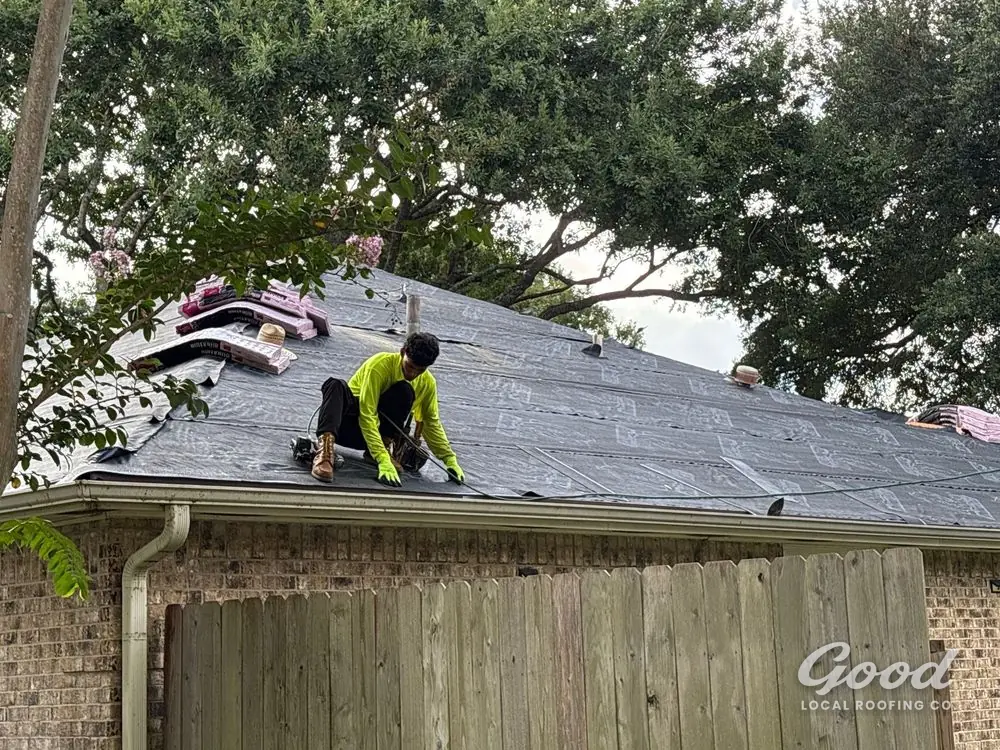
An image from above can be useful, and it can also be wrong. Shadows, stains, tree debris and old repairs can look like damage from a few hundred feet up. A photo taken on the roof, with the location and date noted, is a better record of the condition today.
In Fort Bend County, plenty of neighborhoods have roofs that went on around the same years. When a whole section of a subdivision ages together, these letters tend to arrive in clusters. If a neighbor got one, check your mail.
Read the letter first
Before you call anyone, find four things on the page:
- What they are asking for. Photos, a repair, a replacement, or proof of something already done.
- The deadline. The date to respond and the date the policy renews or ends.
- The stated reason. The condition they say they saw, and where on the roof.
- Who to send proof to. Your agent, an underwriting email, or a portal.
If the reason is vague, ask for it in writing. The Texas Department of Insurance says a company must give you the reason for a nonrenewal in writing if you ask. TDI also says a company may require repairs instead of refusing to renew for poor condition, usually with at least six months to make them. Your letter controls your timeline, so go by its dates.
Call your agent and ask one plain question: “What exactly do you need from me, and by when, to keep this policy?” Write down the answer and who gave it.
Roof age vs. roof condition
In September 2026, TDI announced a rule clarifying that insurers can't decline or refuse to renew a home policy just because the house or the roof is older. They can still make decisions based on the physical condition of the roof and other parts of the home.
That matters for how you answer. If the letter is really about age, ask the company to point to the condition they are relying on. If it is about condition, the best response is evidence of the condition: clear, dated photos of each slope and the specific area they flagged, plus a written description of what was found.
Age still matters for planning. In our field experience, composition shingle roofs here commonly reach the replacement conversation around 10 to 12 years. That is a planning signal, not a verdict. The roof in front of us decides the answer.
Your three real options
1. Document it. If the roof is in sound condition, a set of located, dated photos and a written condition summary may be what the company asked for. Send it through the channel the letter names, before the deadline.
2. Repair it. If the inspection finds a specific problem—a lifted area, a failed boot, a damaged section—a targeted repair with before-and-after photos may answer the letter. Ask the company or your agent whether a repair with photos satisfies their request before you pay for it.
3. Replace it. If the roof is worn across the field, a repair will not hold and you are buying time you will pay for twice. A replacement closes the question. Get the scope in writing, ask about financing if the timing is tight, and keep the completion photos and invoice for your insurer.
Whichever path fits, ask the company or agent for written confirmation once they have received your proof.
What a roofer can and can't do
A roofing contractor can inspect the roof, photograph it, describe the condition, write a repair or replacement estimate and do the work. That is our lane.
A roofer should not tell you what your policy covers, negotiate with your insurer for you or promise an underwriting result. Good Local Roofing Company is a roofing contractor, not a public insurance adjuster or a law firm. Coverage and renewal decisions stay between you, your agent and your insurance company.
If anyone tells you a letter is a sure path to a free roof, slow down. A condition letter is not a storm claim. If storm damage turns up during the inspection, we will show you the photos and you decide whether to talk with your insurer about it.
Send us the letter
Text a photo of the letter and your address to (346) 646-6484. We will read what the company is asking for, schedule a free inspection that documents exactly that, and give you the photos and a written answer: document, repair or replace.
Prefer to talk first? Call (346) 646-6484. Phones are answered 24/7. Our office is at 15002 Lakefair Dr, Suite 102, Richmond, TX 77406.
Already leaning toward a new roof? Get a planning number from our instant roof price before anyone climbs a ladder.
Good questions
Can my insurer drop me just because my roof is old?
TDI announced in September 2026 that insurers can't decline or refuse to renew a home policy simply because the house or roof is older. They can still act on the roof's physical condition. Ask your company which condition it is relying on.
How much time do I have?
Go by the dates in your letter. TDI's home insurance guide says a company may require repairs instead of refusing to renew, usually allowing at least six months, and lists 60 days' notice for nonrenewal on policies bought or renewed in 2024 or later. Confirm your dates with your agent.
Will photos from a roofer be enough?
Sometimes. It depends on what the company asked for. Ask your agent before the inspection so we can photograph and describe exactly what they need.
Is this the same as an insurance claim?
No. A roof-condition or renewal letter is underwriting. A claim is a request for payment after a covered loss. If storm damage shows up during the inspection, we will show you the photos and you decide what to do next.
Do you charge to look at the roof for an insurance letter?
No. The inspection is free for homes in our service area: Richmond, Katy, Cinco Ranch, Fulshear and nearby neighborhoods.
Sources & useful reading
- Texas Department of Insurance: homeowners protected from being denied insurance based on roof age (Sept. 29, 2026)
- Texas Department of Insurance: home insurance guide (nonrenewal, notice and repairs)
- Good Local Roofing Journal: how long a roof lasts in Fort Bend County
- Good Local Roofing: residential roof inspections
Reviewed November 7, 2026. Insurance rules change; check the current TDI pages and your own policy. TDI Help Line: 800-252-3439.
Contractor services only; Good Local Roofing Company does not act as a public insurance adjuster. Coverage and renewal decisions belong to you and your insurer.